
As the 28 October Budget approaches, traders are openly betting against the pound. This essay argues that the real story is not the bet itself, but the growing gap between the people who make decisions and the people who live with the results. I call that gap moral distance – and once you see it, a great deal of modern British life starts to make sense.
There are moments when a country sees itself clearly. Not because someone reveals a secret, but because something that has always been happening suddenly becomes impossible to ignore. The run‑up to the 28 October Budget is one of those moments.
Currency traders are openly betting on the pound falling. Commentators treat it as technical. Politicians treat it as background noise. Markets treat it as opportunity. But the reality is far more consequential: people with the ability to move vast sums of money are playing a game whose results land on everyone else – and the extraordinary thing is that the game is happening in full view, without moral scrutiny, and without anyone connecting the dots.
This is not a story about markets alone. It is a story about a political system that has become market‑facing, an economic system built on promises rather than real value, and a society that has been quietly hollowed out by decades of decisions designed to push consequences onto tomorrow.
Tomorrow has now shown up.
The dots can be connected. Running through the currency markets, the political system, the economy and our wider culture is a single thread: the separation of action from consequence. The people who make the decisions are, more and more often, not the people who live with what those decisions bring. That separation is what this essay is about.
I. Moral Distance: The Thread That Connects Everything
Moral distance is the gap between the person who makes a decision and the person who lives with its consequences. When that gap is small – a builder who lives in the street he builds, a business owner who employs her neighbours – responsibility is felt directly. You see the people affected. You meet them. You have to look them in the eye.
When the gap grows large, something changes. The people affected become abstract. Their lives turn into numbers, positions, risks and forecasts. Decisions stop feeling like choices with victims and start feeling like technical moves in a game. Nobody needs to be cruel for harm to be done. Distance does the work.
This essay follows four forms of moral distance that now shape British economic life:
- Traders are distant from the consequences of the bets they place.
- Politicians are distant from the future costs of the choices they make.
- Institutions are distant from the communities affected by their decisions.
- Markets are distant from the people whose lives become the outcome.
None of these distances is new. What is new is that they now reinforce one another, until markets, money and politics behave as a single system – and a culture that judges actions by whether they pay, rather than by who pays for them, makes the whole arrangement feel normal. The sections that follow take each distance in turn, then ask what it would take to close it.
II. The Game Is Visible – But Its Meaning Isn’t
Currency markets behave like one giant betting arena. Traders wager on the future value of the pound based on expectations of growth, borrowing, political stability and fiscal credibility. When they bet on a weaker pound, they are not expressing an opinion. They are shaping the conditions in which government must operate.
This is not metaphor. It is literal.
For readers less familiar with how this works: a trader who expects the pound to fall can sell pounds today, hoping to buy them back more cheaply later, or use financial contracts that pay out if the pound weakens. One trader makes little difference. But when large funds take the same view at the same time, their selling can help bring about the very fall they are betting on. The forecast becomes part of the cause.
A fall in the pound means:
- higher import costs
- higher energy prices
- higher inflation
- pressure on interest rates
- constraints on government action
- rising costs for households and businesses
The chain is simple. Britain buys much of its energy, food and materials from abroad, priced in other currencies. When the pound buys less, those things cost more. Rising prices push up inflation, which puts pressure on the Bank of England to keep interest rates high – and that, in turn, raises the cost of mortgages, business loans and government borrowing alike.
The people who place the bets are rarely the people who bear the full consequences of those bets. The costs are spread across millions of households and businesses that never entered the game in the first place.
This is the moral inversion at the centre of the system.
It is moral distance in its purest form. The decision and its consequences are separated so completely that the person placing the bet need never see, meet or think about the people who will pay for it.
As Budget day approaches, the familiar ritual is already under way. Journalists speculate about winners and losers. Ministers brief against expectations. Economists debate forecasts. Traders position themselves for gains or losses. Yet beneath the noise sits a quieter question: what kind of economy has become so sensitive to expectations that anticipation itself can help shape outcomes?
The Extraordinary Thing: The Game Is Happening in Full View
This is the part nobody talks about.
Currency speculation is not hidden. It is not subtle. It is not coded.
It is public. It is visible. It is normalised.
Every time the pound moves, the scoreboard updates. Every time traders place bets, the scoreboard reacts. Every time government signals uncertainty, the scoreboard flashes red.
And yet the public conversation treats this as technical rather than moral.
The game is happening in plain sight. The consequences are happening in private. And nobody is connecting the dots.
III. Government and the Governed: The Political System Has Become Market‑Facing
Britain’s political and economic machinery has become increasingly brittle. When a system is fragile, even small market signals can become national events. Governments now govern with markets in mind because markets have become the arbiters of credibility.
Bond yields judge borrowing. Currency markets judge stability. Ratings agencies judge risk. Investor sentiment judges political behaviour.
A brief explanation helps here. When the government borrows, it sells bonds – promises to repay with interest. The bond yield is, in effect, the interest rate investors demand to lend to the state. If they lose confidence, they demand more, and the cost of everything government does rises with it. Ratings agencies, meanwhile, publish grades on how risky a country’s debt appears, and those grades influence what lenders are willing to accept.
This is not democratic accountability. It is market accountability.
And it means the game played in financial markets becomes the game government must respond to.
The issue is not that governments should ignore markets. A government that borrows recklessly, wastes resources or loses credibility will eventually discover that reality matters. The deeper question is why modern states have become so dependent on financial market approval that a week of trading can overshadow years of democratic decision-making. Markets are meant to be one source of information. Increasingly, they function as a source of permission.
The issue is not that markets exist. The issue is that governments, institutions and economies have become organised around satisfying them.
Markets have become powerful because politics, borrowing and economic structure have been built around their reactions. And that creates a second form of moral distance. A government answering to markets is rewarded for looking credible today, while the costs of what it postpones – repairs not made, investment not undertaken, problems not faced – fall on people further down the line, many of whom are too young to vote and some of whom are not yet born. Politicians are held to account by the scoreboard in front of them, not by the future they are shaping.
IV. Money and What It Stands For: The Economic System Enables the Game
The cost of putting something off is almost never the same as the cost of dealing with it. It is almost always bigger, and it is very often paid by someone other than the person who chose to wait.
That is moral distance stretched across time. The person who chooses to wait and the person who pays for the waiting are rarely the same.
For decades, governments, banks and institutions have pushed consequences onto tomorrow. They built a system where money is created as credit, where debt is treated as value, and where promises grow faster than the real things – skills, industries, communities, land, energy – that money is supposed to stand for.
In plain terms: most money today is not printed by the state but created when banks make loans. Every loan is a claim on the future – a promise that value will be produced later to repay it. The modern system increasingly creates those claims on future value faster than it creates the real things that make prosperity possible. Debt grows faster than productive capacity. Asset prices grow faster than wages. Financial wealth grows faster than physical wealth. Each of these is another kind of distance: between money and the things money is meant to represent.
This system works only if everyone keeps believing the promises.
Currency markets are the purest expression of that belief. They trade the future as if it were a commodity. They price political decisions before they happen. They reward instability when instability is profitable.
And because the real economy has been hollowed out – the skills lost, the industries sold, the communities weakened – even small market movements now hit with disproportionate force.
V. Decisions and Places: The Hollowing Out Makes the Consequences Unavoidable
The hollowing out is not abstract. It is visible everywhere:
- towns that have forgotten what they were for
- trades that disappeared in a generation
- public services stretched thin
- wages that buy less every year
- rivers that are no longer safe
- homes priced as assets rather than places to live
This hollowing out rarely makes headlines in one go. It arrives slowly, and then all at once: a long accumulation of choices that only becomes visible when the consequences can no longer be deferred.
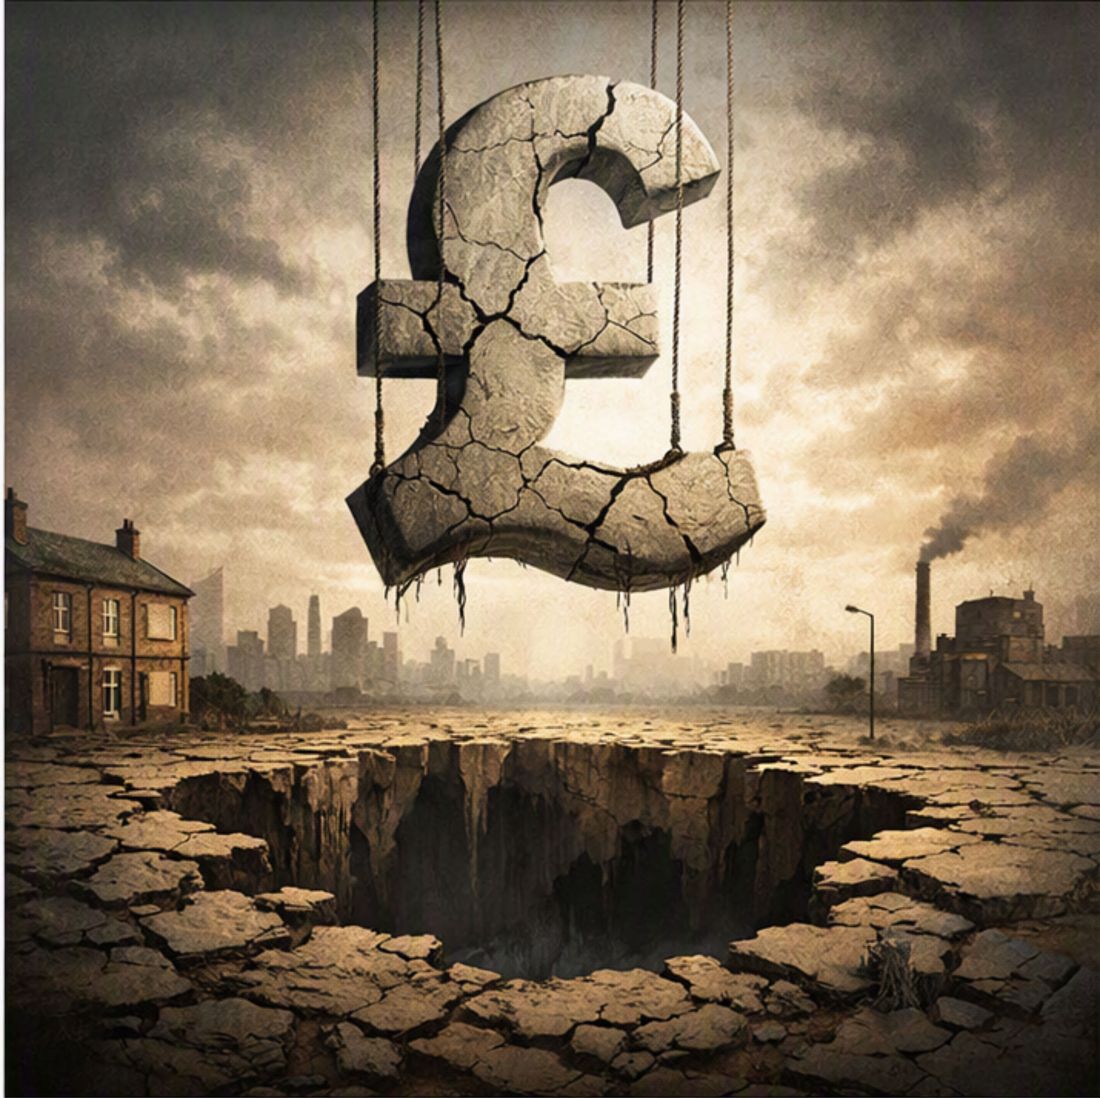
When markets bet against the pound, they are not betting against a number. They are betting against a hollowed‑out real economy.
And the consequences land on the people living inside it.
This is the third form of moral distance. The decisions that shaped these places – to close a plant, sell a firm, cut a service, treat housing as an investment – were mostly taken in boardrooms, trading floors and ministries a long way from the streets that live with the results. Institutions rarely see the town that forgot what it was for. They see a line in a report.
VI. The Cultural Reflex That Keeps the Game Alive
Across British economic life, a cultural reflex has taken hold:
- If it makes money, it’s justified.
- If it’s possible, it’s acceptable.
- If it’s legal, it’s moral.
- If markets reward it, it must be right.
This reflex is not confined to traders. It runs through politics, business, public institutions and even household financial culture. It is the reflex that allowed the creation of money from promises to become the foundation of the modern economy.
It is the reflex that allowed the hollowing out to happen. It is the reflex that allowed consequences to be pushed onto tomorrow. And it is the reflex that allows currency betting to be treated as neutral.
But legality is not morality. Profitability is not justification. Capability is not legitimacy.
The fact that the game is possible does not mean the game is right.
This reflex is what turns moral distance from an accident into a habit. If the only test of an action is whether it pays, nobody ever needs to ask who pays for it. The question that would close the distance – who lives with the consequences of this? – simply never comes up.
VII. Tomorrow Has Shown Up – And the Bill Is Being Paid
Tomorrow rarely arrives with a bang. It arrives the way a damp patch spreads across a ceiling: slowly, and then all at once.
We are living in the “all at once”.
The bill is arriving as:
- a generation that cannot afford a home
- wages that fall behind prices
- public services that no longer stretch
- political systems that cannot act
- markets that shape national outcomes
- a currency vulnerable to speculation
- a future already spent
The bill is not calculated in pounds. It is calculated in lost skills, lost trust, lost places and lost time.
And it cannot be refinanced, rolled over or printed away.
This is what moral distance looks like when it finally closes. Not on the people who made the decisions, but on the people who were furthest from them.
VIII. The Question the Budget Should Confront
The Budget on 28 October will be judged instantly by markets. But the public should judge it on something else:
Does it challenge the cultural assumption that profit is the highest form of value? Or does it reinforce it?
Put another way: does it narrow the distance between those who decide and those who bear the cost – or widen it?
Because until that assumption is confronted:
- markets will continue to play the game
- government will continue to respond to it
- society will continue to absorb the consequences
- and tomorrow will continue to arrive faster than anyone expects
Conclusion: Closing the Distance
This essay began with currency traders, but it was never really about them. The trader is distant from the household. The politician is distant from the future. The institution is distant from the town. The market is distant from the people whose lives become its outcome. And a culture that asks only whether something pays has made all of these distances feel ordinary.
Closing the distance does not mean abolishing markets or pretending that borrowing has no price. It means reconnecting decisions with their consequences: asking, every time, who will live with this – and giving those people a voice before the bill arrives, not after. It means remembering the difference between price and value, between profit and legitimacy, between wealth and prosperity, between markets and society.
Because a society that measures everything by its market price eventually forgets how to recognise value that markets cannot price at all.
The game is in plain sight. The consequences are unavoidable. And the only question left is whether we choose to see it.
Key Terms
- Moral distance – the gap between the people who make a decision and the people who live with its consequences.
- Currency speculation – buying or selling a currency, or contracts linked to it, to profit from changes in its value.
- Bond yield – the effective interest rate a government pays to borrow; it rises when lenders become less confident.
- Ratings agencies – private firms that grade how risky a government’s or company’s debt appears.
- Market‑facing government – a political system that shapes its decisions around how financial markets are expected to react.
- Credit money – money created when banks make loans, rather than printed by the state.
- Hollowing out – the gradual loss of skills, industries, services and community life that sustain a real economy.

