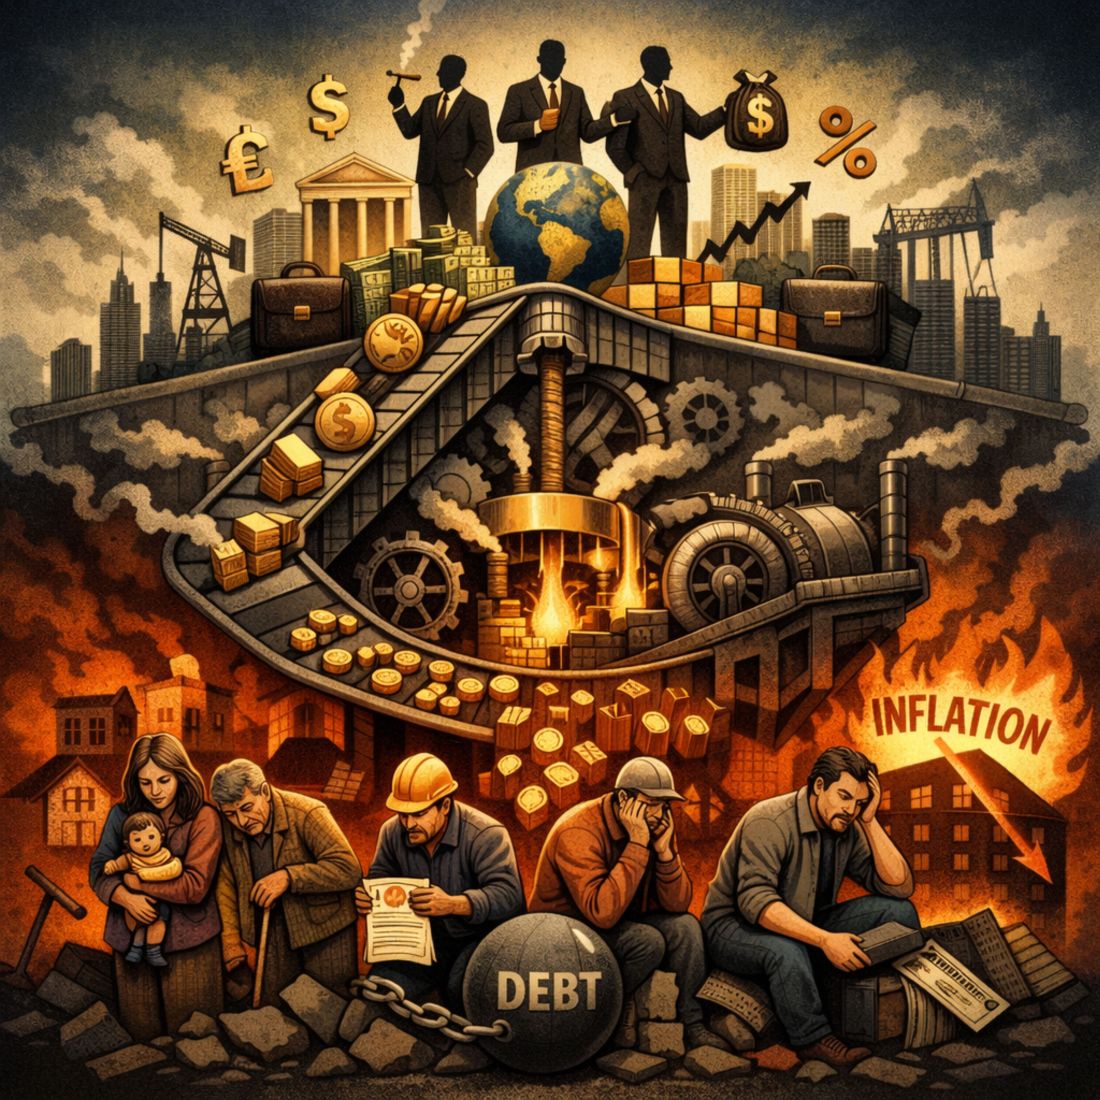

“Created purchasing power became real title over real things, in a system whose rules changed without consent and were never equal, leaving people punished by terms they never chose.”
A Note to the Reader
This is not a book about a secret group controlling everything, nor an argument that every investor, banker, regulator or politician acts with the same knowledge or intent. It is about a system whose parts are widely discussed but whose whole is rarely seen: how money is created, how credit changes ownership, how debt can transfer risk, how incentives shape institutions, and how the consequences reach ordinary life.
The central claim is not that money is imaginary. Money is real in its effects because we accept it, price with it, owe it and organise life around it. The illusion lies in mistaking it for a fixed substance rather than a social and legal system of claims, promises and credit-and in assuming that everyone enters that system on equal terms.
Some examples in these pages describe possibilities; others describe recurring patterns. Intent differs from case to case. A mechanism can produce harm without every participant intending that harm, and ignorance does not erase responsibility. Where facts can be established, they should be established. Where motives cannot, the argument rests on incentives, structures and outcomes rather than mind-reading.
You do not need to arrive from any particular political direction. You may recognise state failure, market failure, inequality, excessive debt, weak regulation, lost local ownership or something else entirely. Each may be part of the picture. The purpose here is to connect the fragments, slowly enough that the reader can test each step.
Introduction: The Part Nobody Sees Whole
Most public arguments begin with a symptom. Prices are rising. Wages are not keeping pace. Housing is out of reach. Services cost more and deliver less. Businesses that appeared viable fail. Governments change, budgets change and promises change, yet many of the pressures remain.
Every group sees part of the problem. The left sees inequality. The right sees state failure. Economists see debt and productivity. Businesses see costs. Households see bills. Journalists see crises. Each may be looking at something real. The difficulty is that a partial truth can still conceal the whole.
Modern finance is divided into specialties. One person understands monetary policy, another acquisition finance, another public borrowing, another regulation, another electoral politics. Expertise makes complex systems possible, but it can also create system blindness: people may understand their part exceptionally well while relying on inherited assumptions about everything around it.
This book follows the connections. It begins with ordinary experience, then moves through money creation, ownership, debt, extraction, institutional incentives and human cost. It does not ask you to accept the conclusion in advance. It asks you to keep looking as each layer is added.
Let’s begin where you are.
You’ve lived your whole life believing money is real. You work for it. You save it. You worry about it. You plan around it. You measure your security by it.
You’ve watched prices rise. You’ve watched wages stall. You’ve watched bills grow heavier. You’ve watched the cost of simply existing climb year after year.
And you’ve probably thought:
- “Everything is getting more expensive.”
- “Life is harder than it used to be.”
- “I’m doing everything right – why does it still feel like I’m falling behind.”
You’re not imagining it. You’re not failing. You’re not alone.
Something has been happening – quietly, steadily, and without your consent.
You’ve seen your high street change. Shops you knew for years disappear. New ones arrive, then vanish. Whole chains collapse overnight.
You’ve seen homes in your area bought up in bulk. You’ve seen rents rise faster than wages. You’ve seen people priced out of the places they grew up in.
You’ve seen utilities sold, resold, and sold again. You’ve seen services decline while costs increase. You’ve seen infrastructure crumble while profits soar.
You’ve seen all of this. You’ve lived through all of this. But few people ever connected the reasons in a way that explained the whole.
And that’s where this conversation begins.
Not with jargon. Not with blame. Not with economics.
But with the simple truth that what you’ve been experiencing is not random, not wholly accidental, and not inevitable.
It is the result of a system that changed – quietly, profoundly – while you were busy living your life.
And the change begins with one idea:
The money used to buy the world around you was never a fixed substance in the way you were taught to imagine it.
But before we open that door fully, we need to walk through the world you did know – the world you trusted – and show how it was reshaped.
1. The World You Thought You Lived In
You grew up believing money worked like this:
- You earn it through work.
- You save it through discipline.
- You borrow it carefully.
- You spend it responsibly.
- You invest it if you’re lucky.
- You protect it because it protects you.
You believed banks lent out savings. You believed companies grew by reinvesting profits. You believed investors used their own wealth. You believed governments spent taxes. You believed markets reflected value.
None of these beliefs were foolish. They were taught to you. They were reinforced everywhere. They were the foundation of your understanding of life.
And for a long time, they were true enough.
But then the system changed.
Quietly. Technically. Mostly beyond public debate. Rarely met with meaningful public consent.
And the rules you were taught stopped being the rules that mattered.
2. The World You Actually Live In
In the modern system, much of the money used for major purchases enters circulation as bank credit before the income needed to repay it has been earned.
When a major investor wants to buy:
- a chain of shops
- a utility
- a housing portfolio
- a stretch of land
- a transport network
- a piece of national infrastructure
they may not rely primarily on accumulated savings, retained profits or existing wealth.
They arrange credit through banks and other lenders. When a commercial bank makes a loan, it normally creates a matching deposit: new spendable money appears within the banking system, paired with a debt that must be serviced and repaid.
And because everyone agrees to treat it as real, it becomes real.
This is the moment where the world you thought you lived in diverges from the world you actually live in.
Because while you were earning money through labour, others were gaining access to newly created purchasing power through credit.
While you were saving for a deposit, others were using large credit facilities to buy whole housing portfolios.
While you were budgeting for bills, others could borrow at scale to buy the companies that send those bills.
While you were trying to keep up, others were using credit-created purchasing power to reshape ownership around you.
3. The Privilege of Creation
There is a deeper implication in what you have just read. It is not simply that commercial banks create most new money when they lend. It is that much of the purchasing power used to buy the existing world did not have to be earned, saved or accumulated before it was deployed.
That changes the possible scale of ownership. If every acquisition had depended principally on savings already set aside, retained profits already made or wealth already realised, the pool available for buying companies, homes, land and infrastructure would have been smaller. Deals would still have happened. Wealth would still have concentrated. But not with the same speed, reach or leverage.
Credit creation did not merely finance a larger economy. It enlarged the power to acquire the economy that already existed.
A worker normally spends after being paid. A saver invests after accumulating. A household proves it can service a mortgage from income. Large borrowers also face tests, prices and limits, but those with acceptable collateral, scale and institutional access can command purchasing power far beyond the cash they already hold. The bank does not hand them value without an obligation; it creates a deposit and a matching debt. Yet the deposit can purchase a real asset now, while repayment is pushed into the future.
This distinction matters. Bank lending is not literally limitless, costless or consequence-free. It is constrained by regulation, capital, liquidity, profitability, collateral, borrower demand and monetary policy. Loans can fail and money is destroyed when bank debt is repaid. But within those constraints, access is profoundly unequal. The decisive privilege is not freedom from repayment. It is the ability to bring forward large amounts of purchasing power and decide what becomes owned before most people have had any comparable chance to earn or save.
This is the golden thread running through the book: without credit creation on this scale, many concentrations of ownership could not have developed in the form, at the speed or to the extent that they did. Homes could not have been bid away from wages so rapidly. Companies could not have been acquired with obligations placed on their own future cash flows so extensively. Public assets and essential services could not have been drawn into such large financial structures so easily.
Created purchasing power became real title over real things.
Legal Does Not Mean Neutral
None of this sits outside the law. Banking licences, company law, insolvency rules, security over assets, tax treatment, acquisition structures, fiscal rules and regulatory permissions make it possible.
That legality is not incidental. Successive governments and parliaments have maintained, revised or extended the framework across generations, often because each part appeared defensible on its own: more lending, deeper markets, easier transactions, private investment, economic growth.
The shocking point is therefore not that law was broken. It is that lawful processes could combine to produce outcomes most citizens were never invited to understand as a whole.
Legality can establish permission. It cannot, by itself, establish fairness, wisdom or democratic consent.
Politicians did not have to design every consequence or understand every mechanism to carry responsibility. Those who seek high office inherit a duty to understand the monetary, fiscal and legal architecture they govern. Ignorance may be widespread and sincere. At that level, it is still consequential.
4. The Hidden Mechanisms
People hear financial terms all the time – “leveraged buyout,” “loading a company with debt,” “special dividend,” “restructuring,” “credit event” – and they assume it’s specialist jargon.
They assume it’s complicated. They assume it’s legitimate. They assume it’s something “finance people” understand.
That assumption helps keep the mechanism out of ordinary view.
The jargon can act like a curtain. Behind it, the basic mechanism can be simple-and, in some cases, devastating.
Let’s walk through one of the most important ones.
What It Really Means When a Buyer Loads a Chain With Debt
Imagine a chain of shops you’ve known all your life. It’s part of the fabric of everyday life.
A large investment group decides to buy it.
People assume:
- they must be wealthy
- they must have huge reserves
- they must be using money from investors
Often, that is not the whole story.
They can use large amounts of borrowed money, some of it created through bank lending.
Now here is the part many people never encounter:
The buyer doesn’t take on the debt – the chain does.
The debt is placed on the company being acquired, not on the people doing the acquiring.
So the chain-the shops, the staff and the supply network-can emerge carrying debt incurred to finance its own acquisition.
The buyer walks away owning the chain. The chain walks away owing the debt.
It’s like buying a house and making the house itself take out the mortgage.
Then the buyer pays themselves a “special dividend” – real money – taken from the debt they just put on the chain.
The buyer gets richer. The chain gets weaker.
Then the chain:
- cuts staff
- cuts wages
- cuts maintenance
- cuts stock quality
- closes stores
People see the decline and think:
- “The chain must be struggling.”
- “Competition must be too strong.”
- “Times must be changing.”
Competition or changing markets may play a part. But where acquisition debt and extraction have weakened the business, those financial decisions can be decisive.
It may have been hollowed out from the inside.
If it later collapses, the buyer may already have recovered fees, dividends or other returns while workers, suppliers, creditors and communities carry much of the loss.
For some buyers, collapse does not erase the returns already extracted. Whether intended or not, the incentives can reward decisions that leave the company less able to survive.
5. The Same Pattern, Across the Economy
Variations of this pattern-credit creation, leveraged purchase, debt loading and extraction-can be found across:
- high street shops
- utilities
- housing
- transport
- infrastructure
- care homes
- nurseries
- supermarkets
- energy networks
Everyday people see the symptoms:
- rising prices
- declining services
- collapsing chains
- disappearing shops
- unaffordable housing
- failing infrastructure
But the underlying mechanisms are rarely presented together.
Because the mechanism is hidden behind jargon.
And because most discussion still treats money as a neutral thing rather than a system of relationships, permissions and obligations.
6. The Moral Dimension: When Money Becomes the Value System of Life
The same architecture that expands ownership also shapes valuation. Once access to created credit determines who can buy, finance ceases to be only a means of exchange. It becomes a gatekeeper: deciding which projects are fundable, which assets are desirable and which lives appear secure enough to deserve further credit.
The financial institutions that extend credit and shape ownership also help construct the systems through which the public is assessed.
They run:
- credit scoring
- affordability checks
- risk assessments
- debt recovery
- financial compliance
They decide who is “responsible.” They decide who is “risky.” They decide who is “worthy.”
They therefore exercise power inside a system whose rules they have helped to define.
Because money has become a central value system of life, these judgements can influence:
- whether someone can rent a home
- whether someone can borrow and on what terms
- whether someone can obtain essential services without paying in advance
- whether someone can access financial products and opportunities
- whether someone can survive a crisis
These systems have power over:
- mental health
- family stability
- physical wellbeing
- dignity
- hope
- life trajectories
In extreme cases, they have power over life and death.
And yet the system can still appear fair because the public is rarely shown how differently access to money and credit is distributed.
7. The Human Cost: People Punished by Rules They Never Knew Changed
Think of the people who saved all their lives. Who worked hard. Who lived carefully. Who believed they were safe.
They thought standing still was enough.
But the system was always moving – always extracting – always pulling value upward.
People weren’t standing still. They were being dragged backwards.
And when they struggled, the system blamed them.
“You didn’t save enough.” “You didn’t work hard enough.” “You didn’t plan well enough.” “You didn’t keep up.”
But how could they keep up with a system where:
- new credit purchasing power is accessible to some on far greater terms
- repayment burdens and losses fall on others
- assets move upward
- costs move downward
- responsibility is individual
- power is centralised
They couldn’t. Against those unequal terms, keeping up may be impossible however responsibly someone behaves.
8. The Truth about Money Today: You Were Never Told the Whole Story
People aren’t stupid. They aren’t lazy. They aren’t irresponsible.
They were simply never told the rules.
They were taught:
- money is real
- debt is dangerous
- saving is noble
- hard work pays off
- markets are fair
- politicians protect them
None of those ideas was wholly foolish; each was incomplete, and some became less reliable as the system changed.
The rules changed. The system changed. The incentives changed.
But the public was rarely shown how the changes connected.
And because nobody told them, they kept playing a game that no longer existed.
What This Argument Is-and Is Not
This argument does not require a hidden command centre. It does not claim that every debt is harmful, every market is false, every company is predatory, every investor is malicious, every regulator is captured or every politician is corrupt.
It argues that incentives matter; that systems evolve; that complexity hides consequences; and that harm can be reproduced by people who each see only part of what they are sustaining.
How Intelligent People Believe Incomplete Things
Complexity does not merely confuse the public. It fragments understanding among experts. Institutions train people to solve the problems directly in front of them, reward them for fitting accepted models and give them little reason to question the assumptions beneath those models. A banker may understand credit but not community loss. A regulator may understand compliance but not ownership extraction. A politician may understand a budget but not the full monetary structure within which it operates. None needs to be foolish or dishonest for the whole to remain unseen.
Responsibility still remains. People who seek power over public money, regulation, ownership or essential services have a duty to understand the systems they shape. Not knowing may explain a decision; it does not make its consequences disappear. The moral question is therefore larger than blame: what should people in positions of power be expected to know, and what should they do when the system rewards them for not looking too far?
A Ladder of Understanding
Understanding usually arrives in stages. First, life feels harder. Then the reader sees that prices, wages, housing and services are connected. Next comes the role of credit: new purchasing power can enter through debt before it is earned through production. Then comes ownership: access to credit can outrun access to wages. Finally comes the institutional question: how can so many people participate in a system whose combined effects so few are positioned to see? Each step matters. None requires the reader to surrender judgement.
9. How the System Sustains Itself
Why the illusion doesn’t break – and why ordinary people keep the system alive without realising it
By now, you’ve seen how the system works. You’ve seen how bank deposits can be created through lending. You’ve seen how assets are bought. You’ve seen how debt can be used as an instrument of control or extraction. You’ve seen how value is extracted. You’ve seen how collapse can be engineered or made more likely by financial decisions. You’ve seen how ordinary people carry the cost.
And naturally, a question rises:
“If this is how the system works, why hasn’t it fallen apart?” “Why doesn’t anyone stop it?” “Why do people keep voting for the same thing?”
The answer is not simple – but it is clear.
The system sustains itself through layers. Layers of belief. Layers of pressure. Layers of narrative. Layers of power.
Let’s walk through them gently.
A. The Psychological Layer: Belief Holds the Illusion Together
The system’s legitimacy depends partly on people treating every pound as though it reached every holder through the same kind of effort and access.
They believe:
- banks lend savings
- investors use wealth
- companies grow through profit
- markets reflect value
- debt is dangerous
- collapse is accidental
These beliefs act like glue.
They hold the illusion together.
If people understood that bank lending creates new deposits, that access to this purchasing power is unequal, and that financial decisions can make collapse and extraction more likely, the system’s legitimacy would face much harder questions.
So the system depends on belief.
Belief is the foundation. Belief is the shield. Belief is the fuel.
B. The Political Layer: Market-Facing Governance
Elected governments are accountable to citizens, but in practice they must also respond to financial markets, lenders, institutions and the expectations built around them.
Markets react instantly. Citizens react slowly.
Markets can react within minutes. Citizens usually respond through slower political processes and often absorb the consequences in the meantime.
Markets demand stability. Citizens demand hope.
So politicians:
- deregulate finance
- privatise assets
- protect capital flows
- avoid policies that upset investors
- present political choices as if financial scarcity alone determined them
- reinforce the belief that access to money reflects earned value alone
This does not require conspiracy. It can arise from aligned incentives, inherited assumptions and constrained choices.
And because the architecture is rarely explained as a whole, elections are usually fought over budgets and personalities rather than the monetary and ownership system beneath them.
C. The Institutional Layer: Regulators Within the System
People assume regulators protect them.
Yet regulators can be limited by the ecosystems in which they work. They may:
- come from the same institutions they regulate
- use the same models
- share the same worldview
- rely on the same data
- speak the same jargon
- move between roles in the same industry
They are not outside the ecosystem they oversee.
They mark the system’s homework. They validate the system’s decisions. They reinforce the system’s legitimacy.
Technical language also makes meaningful public scrutiny harder.
D. The Social Layer: When Survival Consumes Attention
Most people are not apathetic. They are exhausted.
They are dealing with:
- rising costs
- stagnant wages
- insecure work
- unstable housing
- family pressures
- health challenges
- debt burdens
- constant uncertainty
People don’t have time to analyse monetary policy. They don’t have energy to decode financial jargon. They don’t have space to question the system.
Survival consumes attention. One effect is that exhausted people have little capacity left to examine the structures around them.
E. The Narrative Layer: The Stories That Shape Interpretation
The system tells stories.
Stories like:
- “The market knows best.”
- “Competition makes things better.”
- “Privatisation increases efficiency.”
- “Debt is a personal responsibility.”
- “If you’re struggling, you must have done something wrong.”
- “If a company collapses, it’s because it failed.”
These stories are repeated everywhere:
- in media
- in politics
- in advertising
- in education
- in everyday conversation
They shape how people interpret what they see.
They turn structural harm into personal failure. They can make financially induced decline appear natural. They turn extraction into “business.”
Narrative is the anaesthetic. It numbs the truth.
F. The Economic Layer: Inflation, Debt and Dependence
Inflation erodes savings. Debt creates dependency. Asset inflation rewards owners. Wage stagnation punishes workers.
Together, these forces can leave people:
- compliant
- anxious
- dependent
- distracted
- divided
People chase rising costs. People fear losing what little they have. People cling to the hope of stability.
Fear of losing security can then sustain the arrangements that produced the insecurity.
G. The Moral Layer: Blame and Shame
This is the cruelest part.
The system convinces people that their struggles are their fault.
“You didn’t save enough.” “You didn’t work hard enough.” “You didn’t plan well enough.” “You didn’t keep up.” “You made bad choices.” “You should have known better.”
Blame keeps people quiet. Blame keeps people ashamed. Blame keeps people isolated.
Blame prevents people from seeing the truth:
They were punished by rules they never knew changed.
10. When a System Takes Too Much
By now, you’ve seen how the system works. You’ve seen how bank deposits can be created through lending. You’ve seen how assets are bought. You’ve seen how debt can be used as an instrument of control or extraction. You’ve seen how value is extracted. You’ve seen how collapse can be engineered or made more likely by financial decisions. You’ve seen how ordinary people carry the cost. You’ve seen how belief, politics, institutions, narratives, and pressure keep the system alive.
But there’s one more truth – one that matters more than any other:
The present model is reaching limits because it has taken too much from the foundations on which it depends.
Not because people rose up. Not because governments changed direction. Not because regulators intervened. Not because markets became moral.
It is straining because extraction has advanced further than wages, services, infrastructure and communities can indefinitely absorb.
Let’s walk through this slowly.
A. Extraction Has Outpaced Life
For decades, the system has been pulling value upward:
- from wages
- from savings
- from housing
- from public services
- from infrastructure
- from communities
- from local economies
- from future generations
At first, people absorbed the pressure. They worked harder. They borrowed more. They cut back. They adapted.
But extraction didn’t stop. It accelerated.
And now, for millions of people, there is nothing left to give.
Governments feel this too.
They rely on:
- taxes
- fees
- charges
- fines
- duties
- levies
- borrowing
But when people have nothing left, governments have nothing left to take.
So they turn to the only tool they have left:
They take more from people who can’t afford it.
Not necessarily because they want to, but because the choices presented to them are constrained by the system they inherited.
This is why governments feel desperate. This is why public services are collapsing. This is why everything feels like it’s fraying.
The system is consuming the very people it depends on.
B. Public Borrowing: A Symptom of Strain
Public borrowing is not the whole story, but it belongs in it because the purpose of borrowing matters as much as the headline total.
When governments borrow, people imagine:
- “We must be investing in the future.”
- “We must be building something.”
- “We must be preparing for growth.”
But increasingly, public borrowing is not used to build. It’s used to patch holes created by decades of extraction.
Governments borrow to:
- keep services running
- keep infrastructure functioning
- keep hospitals open
- keep schools afloat
- keep transport moving
- keep social care from collapsing
- keep the basics of life from falling apart
Borrowing becomes a way to delay the consequences of a system that has already hollowed out the foundations.
It’s not investment. It’s triage.
And because governments are borrowing to fill gaps rather than build value, the debt grows faster than the capacity to repay it.
This is not a failure of government. It’s a symptom of a system that has taken too much.
C. GDP: When the Measure Becomes the Mission
Public debt is commonly expressed as a percentage of gross domestic product. There is a practical reason: the same cash debt can be easier or harder to carry depending on the size and income of the economy supporting it. The ratio helps compare an obligation with the economic base from which taxes and repayments may come.
But once stability, borrowing capacity and political credibility are narrated through that ratio, growth in GDP becomes more than a desirable outcome. It becomes a way of keeping debt looking supportable. A larger denominator can make a larger stock of debt appear more manageable. This does not mean governments can borrow without limit, or that GDP statistics conceal the cash amount. It means the political story of sustainability becomes tied to continued measured expansion.
GDP then begins to act not only as a measure but as a governing pressure. Activities that produce priced transactions count readily. Selling care counts; unpaid care usually does not. Rebuilding after damage can add to output even when the damage itself represents a loss. Higher rents can enlarge measured activity while making households less secure. A forest may sit only partially inside the national accounts until it is cut, sold or converted into a priced asset.
GDP was not designed to measure the whole of human progress, and official statisticians increasingly publish measures beyond it. The danger comes when a measure of marketed production is treated as if it were a complete account of value. What cannot be priced becomes easier to neglect. What can be monetised becomes easier to justify.
This is how the logic spreads. Debt calls for growth. Growth calls for more measurable activity. Measurement rewards monetisation. Monetisation reaches into care, housing, education, health, nature, attention and time. Things once valued because they sustained life are recast as resources, services, assets and revenue streams.
The deepest distortion is not that GDP measures nothing useful. It is that what it cannot adequately measure can begin to look as though it has no value.
D. The Illusion of Stability Is Breaking
For years, the system maintained the illusion of stability by:
- inflating asset prices
- suppressing wages
- expanding credit
- privatising services
- selling public assets
- loading companies with debt
- extracting value from everything
But every illusion has limits.
You can only:
- raise rents so far
- inflate house prices so high
- suppress wages so long
- cut services so deeply
- load companies with so much debt
- extract so much value
- privatise so many assets
Eventually, the system reaches a point where:
- people can’t afford to live
- services can’t function
- infrastructure can’t cope
- companies can’t survive
- governments can’t stabilise
- communities can’t absorb the pressure
That is the direction in which the present pressures are pushing us.
Not at the end of the world. Not at the collapse of society. But at the end of a system that has exhausted its own foundations.
E. Even Those at the Top Depend on Stability
This is the part people rarely consider.
The system doesn’t just fail the public. It fails itself.
Because when extraction reaches its limit:
- assets lose value
- debt becomes unmanageable
- markets become unstable
- political legitimacy erodes
- social cohesion weakens
- economic growth stalls
- confidence collapses
Even those at the pinnacle – the ones who benefited most – are not safe.
Their wealth depends on:
- stable markets
- functioning governments
- compliant populations
- predictable systems
- reliable infrastructure
- social order
When the system strains, those foundations shake.
The illusion protects them – until it doesn’t.
F. The Truth of this Moment: A Model Reaching Its Limits
This is the truth we need to deliver softly:
The present model is reaching its limit not because people defeated it, but because it consumed too much and left too little behind.
It is reaching those limits because:
- people cannot absorb more extraction
- governments face political and practical limits on raising revenue
- services cannot withstand more cuts
- companies cannot survive more debt
- communities cannot endure more pressure
- markets cannot hide more instability
- public belief becomes harder to sustain
The present model is reaching its limits because it has reached the natural limit of what life can sustain.
And the penny dropping – the moment of understanding this – is enough here, in this book for now.
Not action. Not rebellion. Not solutions.
Just awareness.
Because awareness is the first step toward seeing clearly.
And seeing clearly is the first step toward whatever comes next.
11. The Reality We Are Living Through
Let’s pause here.
Because if the penny has dropped – if you have truly seen the system for what it is – that is enough for now.
Understanding is already a profound act. It is already a form of change.
So let’s reflect for a moment about the reality we are living through.
We live in a world where:
- money has become a central value system of life
- more decisions are filtered through cost, price, profit and affordability
- public services are judged by financial metrics
- human needs are reframed as financial burdens
- communities are treated as markets
- people are treated as units of productivity
- wellbeing is treated as an economic output
This did not arise from one decision or one group. It is the cumulative result of decades of financialisation: life increasingly reshaped around monetary measures rather than human ends.
And we have all taken part.
Not maliciously. Not knowingly. Not deliberately.
But through:
- accepting the rules we were taught
- believing the stories we were told
- trusting the systems we grew up with
- fearing exclusion
- needing security
- wanting stability
- trying to survive
Many people sensed something was wrong. They felt the pressure. They saw the cracks. They noticed the contradictions.
But instead of speaking out, they stayed quiet. Not because they didn’t care – but because the system made them feel powerless.
“Take part or be excluded.” “Play the game or fall behind.” “Adapt or suffer.”
And when enough people accept a system – even reluctantly – the system becomes normal.
That’s how we arrived here.
The pressure is reinforced by what the country chooses to count. If national success is repeatedly reduced to growth in priced activity, then more borrowing, more transactions and more extraction can appear as progress even when security, care, belonging and ecological resilience are deteriorating.
The measure does not cause every decision. It helps decide which consequences remain visible.
A world where:
- reliance on benefits has grown
- food banks have become normal
- mental distress is widely reported
- debt is a constant companion
- insecurity is widespread
- social pressures accumulate
- communities feel hollowed out
- people feel alone even when surrounded by others
These are not isolated issues. They are symptoms of a deeper truth:
Life has been financialised, stripped, hollowed out, and reshaped around money – under the guise of being reshaped around need.
But most of what we call “need” today is actually “want” – wants created by a system that profits from insecurity, aspiration, and fear.
And while people chase wants, their basic needs – the simple, essential foundations of life – have become harder and harder to meet.
Growing numbers can no longer meet those needs without:
- benefits
- charity
- debt
That is the reality we are living through.
And seeing it clearly is the beginning of something important.
12. The Necessary Turn: The Reality We Need to Embrace
Now let’s turn – slowly, softly – toward the reality we need to embrace.
Not a list of actions. Not a call to arms. Not a set of instructions.
Just a direction. A shift in understanding. A different way of seeing life.
Because once you see that money has become the central value system of everything, you can also see that it doesn’t have to be.
Human beings did not evolve to live money-centric lives.
We evolved to live people-centric lives.
Lives built around:
- relationships
- community
- shared responsibility
- mutual support
- contribution
- meaning
- dignity
- purpose
- care
Money was meant to be a tool. A way to organise exchange. A way to coordinate effort. A way to support life.
But somewhere along the way, money stopped being a tool and became the measure of everything.
It became:
- the measure of worth
- the measure of success
- the measure of security
- the measure of identity
- the measure of possibility
- the measure of morality
And when money becomes the measure of everything, people become measured by money.
That is the world we have been living in.
But it is not the world we have to continue living in.
Because the present model is reaching visible limits.
Not because people fought it. Not because governments changed direction. Not because regulators intervened.
It is under strain because it consumed too much and left too little behind.
It is reaching those limits because:
- people cannot absorb more extraction
- governments face political and practical limits on raising revenue
- services cannot withstand more cuts
- companies cannot survive more debt
- communities cannot endure more pressure
- markets cannot hide more instability
- public belief becomes harder to sustain
It is approaching the practical limits of what people, institutions and the living world can sustain.
And that means something important:
The future cannot remain money-centric. It will have to become people-centric again.
Not overnight. Not through revolution. Not through ideology.
But through necessity.
Through the simple truth that life cannot continue on the terms set by a system that has already hollowed itself out.
People-centric living is not necessarily utopian. Cooperation, care and relationship have always been essential to human survival. It is the way communities survive. It is the way societies endure. It is the way people thrive.
And as the money-centric system strains, cracks, and falters, people will begin – slowly, quietly, naturally – to rediscover what it means to live in ways that are:
- grounded
- human
- relational
- communal
- meaningful
- sustainable
The argument for this book ends without a programme or a roadmap. Its purpose is more basic: to make the structure visible, so that whatever comes next begins from a clearer account of the world as it is.
The penny dropping is enough.
Because once someone sees these connections clearly, they are difficult to ignore. And once they become difficult to ignore, people begin-in their own way, in their own time-to shift towards a different way of living.
A way of living that is not built around money. But built around people.
And that is the beginning of everything that comes next.
Afterword: What to Hold On To
This book has not asked you to choose a tribe. It has asked you to notice connections: between credit and ownership, ownership and power, power and narrative, narrative and the judgements made about ordinary lives.
The point is not that one explanation replaces every other explanation. It is that no budget, election or policy can be understood fully while the monetary and ownership system beneath it remains invisible.
Before anything different can be built, people have to understand what they are standing inside. That does not guarantee agreement. It does make a more honest disagreement possible.