
A Note from Adam
I haven’t written this because I’ve only just begun to understand these problems. I’m doing so because explaining them has never been easy. Even many academics and economists are so committed to the system we have that they simply cannot see another way. It has always been easier for them to believe that those who are struggling brought it on themselves than to confront the alternative – that the system they defend may feel stable for those who benefit from it, but it is not fair, and it is not how things should be.
The reason for writing this now is simple: people everywhere can feel that things no longer add up. There is a shared concern about what happens next, and we will all face difficult choices in the years ahead. Those choices become harder – and the times become more confusing – if we still don’t understand what is happening or what has caused so many of the problems we now need to move beyond and leave behind.
This essay is an attempt to make that understanding easier. Not to assign blame, not to provoke anger, but to give people a clearer picture of the forces shaping their lives. If we can see the system for what it is, we can begin to imagine something better.
1. The world people think they live in
Money sits at the heart of everything. Every decision, every direction, every journey, every relationship we have today relates to money in some way and at some level, to the point that we don’t even see it or consciously think about it being there anymore.
We think about money in simple terms: as a store of value, and more significantly as the measurement of value for everything we do, need, own and imagine for the future – because that’s the way money works; right?
To many of us, money is real, quantifiable and tangible. It’s like the coins and notes we sometimes still use, and we assume the digital version-the figures on a bank statement, the numbers that move when we tap a card-is just the same thing in another form. We build our lives, our hopes, our sense of security on that assumption.
We are also quietly told a story: that if we work hard, manage our money, avoid “bad choices”, the system will look after us. That wages are fair, that prices are natural, that debt is a personal failing, that the economy is something that happens “out there” while we get on with our lives.
This is the world people believe they inhabit. Familiar. Rational. Moral. And it’s the world that allows the real system to operate without being seen.
2. The first crack in the illusion
What we don’t think about-or in many cases don’t realise-is that the relationship and understanding of money we have is not the same for everyone, and that the way we interact, use, value and respect money makes us vulnerable to its influence, power and presence.
Historically, there was a time when banking really did look like the story we still tell ourselves: deposits, lending, interest, savings. But in the 20th century, something fundamental changed. We moved away from a system where the money in circulation had to relate directly to the amount of gold held-the gold standard-and into a system called fiat, where money is created at will.
Fiat simply means: “let it be so”. Money exists because the system declares it exists.
Today, every pound enters the economy as someone’s debt. Money is not a pile of coins waiting to be lent out; it is a number typed into existence when a loan is made, a bond is issued, or a government borrows.
Yes, you heard that correctly – money today is actually debt.
Most people never realise this. Not because they are foolish, but because nobody ever told them.
While they were living their lives, trusting the system, the system was quietly reshaping the world around them using a logic they were never allowed to see.
The first crack in the illusion appears when you ask simple questions:
- If every country is in debt, who is the creditor?
- If banks lend money they don’t already have, what exactly are we borrowing?
- If money can be created from nothing, why is anyone going without?
Once you see that money is created as debt, you can no longer pretend the system is neutral.
3. The reveal: how the system actually works
Modern money is not mined, earned, or discovered. It is created-conjured into existence through government borrowing, bank lending, and central‑bank intervention.
Every pound enters the economy as someone’s debt; every debt becomes someone else’s asset.
In plain language:
- Fiat money: Money that exists because the system says it does, not because it is backed by anything physical.
- Credit creation: When a bank types new numbers into your account and calls it a loan. The money did not exist before that moment.
- Debt as money: The numbers we call “money” in the system are, in reality, records of who owes what to whom.
- Interest: The extra amount that must be paid back on top of the loan. This is not created with the loan; it must be extracted from somewhere else in the real economy.
Every loan requires:
- principal
- interest
- fees
None of that interest is created with the original money. It has to come from someone’s labour, someone’s time, someone’s sacrifice.
So the system works like this:
Money is created as debt. Debt must be repaid with interest. Interest must be taken from the real economy.
The more money is created, the more extraction is required.
This is why:
- wages stagnate
- public services collapse
- housing becomes unaffordable
- debt becomes permanent
- inequality skyrockets
People are not suffering because the system is broken. They are suffering because the system is working exactly as it should.
4. The consequence: how money creation bought the real world
Before money, people traded directly: food, labour, tools, shelter. Value was agreed in the moment, between people who could see each other and the reality of what they were exchanging.
There were always those who abused power-leaders, warriors, officials who took more than they needed-but they were limited by what physically existed.
Fiat money and credit creation removed that limit.
Money created from nothing has been used to buy everything real.
Banks, asset managers, private‑equity firms, and multinational corporations have used newly created credit to acquire:
- public infrastructure
- utilities
- housing stock
- farmland
- logistics networks
- media companies
- technology platforms
- entire industries
These purchases were not funded by savings or productive profit. They were funded by credit creation-money that did not exist until the moment it was lent.
Massive swathes of public infrastructure, private property, businesses, and capital ownership have been transferred into private hands not because those buyers had earned the wealth, but because the system gave them access to unreal money with real purchasing power.
Ordinary people, earning wages, paying bills, could never compete with that.
This is why:
- housing became an investment class instead of a human necessity
- private equity owns half the high street
- utilities and transport were sold off and now charge the public for access to what was once collectively owned
- monopolies exploded, and “markets” quietly turned into systems of rent‑seeking
At the same time, people at the bottom of this system are told that the minimum wage is enough to live on.
It isn’t.
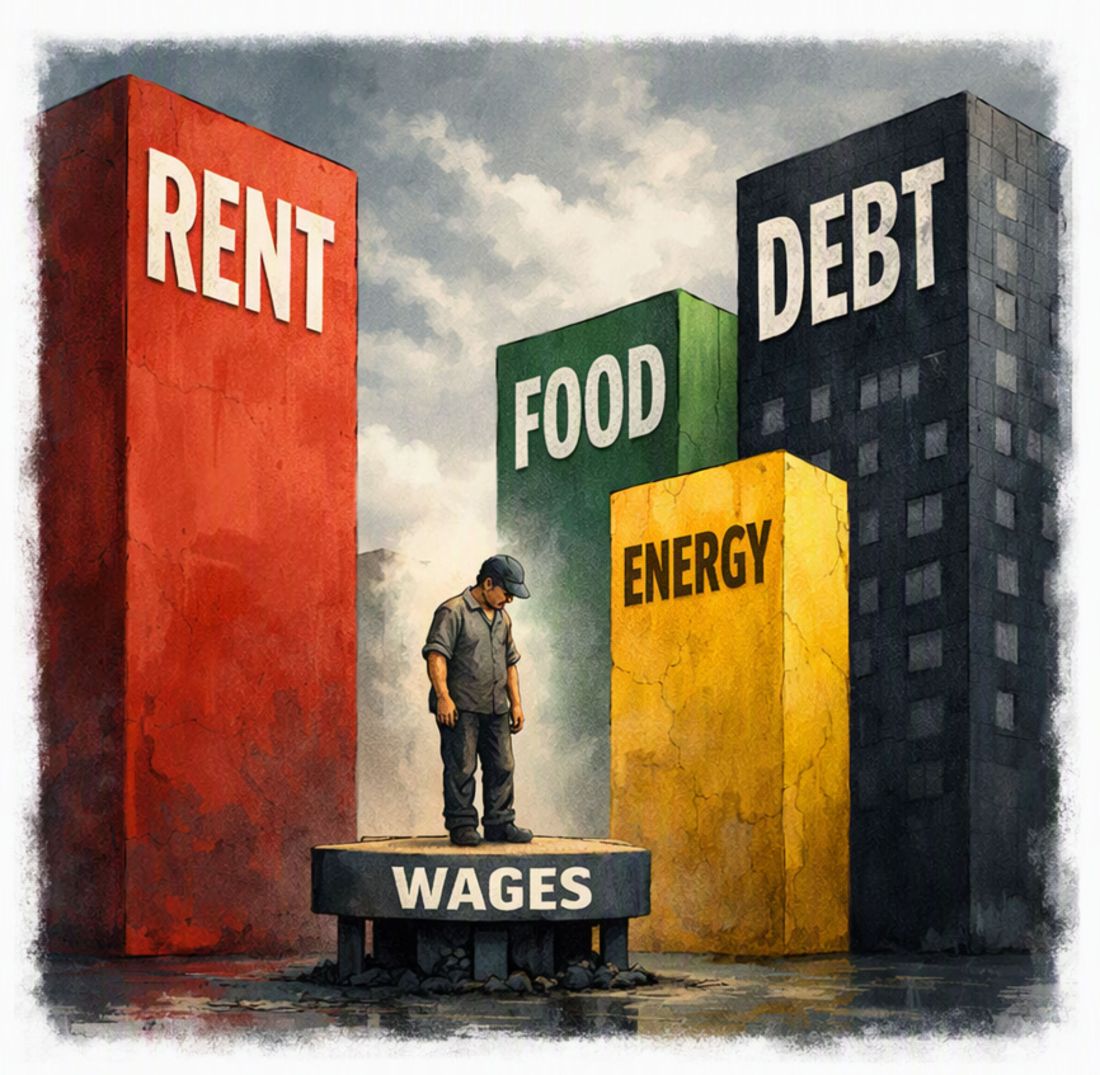
A wage that cannot cover rent, food, transport, heating, clothing, and basic security is not a living wage; it is a survival wage.
Survival for those on the minimum wage is only possible through:
- benefits
- charity
- debt
No amount of budgeting can fix a wage that was never designed to cover the cost of living. Yet those who struggle are treated as if they are responsible for the plight they are in-told to “manage better”, “work more”, “stop wasting money”-while the system quietly ensures that their struggle continues.
The hardship is manufactured. The shame is manufactured. The dependence is manufactured.
And now, the same mechanism is inflating the AI bubble.
Vast flows of credit are pouring into AI companies whose current productivity and wage‑earning capacity cannot justify their valuations.
The system is funding the very technology that threatens to remove jobs, reduce wages, and undermine the income streams required to service the debt that created the bubble in the first place.
It is the snake eating its own tail: a debt‑based system financing tools that erode the labour base that keeps that system alive.
This is why some of the loudest voices in technology have suddenly begun talking about “AI takeover”, “existential risk”, and “superintelligence”. These narratives function as brakes-attempts to slow down a bubble that could become the straw that breaks the system’s back, if something else doesn’t get there first.
5. The betrayal: people were told this was “responsible economics”
None of this was sold to the public as extraction. It was sold as responsibility.
People were told:
- austerity is necessary
- inflation is accidental
- debt is dangerous (for them)
- privatisation is efficient
- markets are natural
- minimum wage is enough
- benefits are a safety net, not a dependency trap
They were told that if they struggled, it was because they had failed-failed to work hard enough, failed to manage money, failed to be “responsible”.
In reality:
- debt enriches creditors
- inflation enriches asset holders
- austerity protects the financial system
- credit creation fuels monopolies
- monopolies extract from the public
- low wages and high costs create permanent dependence on benefits, charity, or debt
People weren’t stupid. They were never shown how the system works. They were never told that money is created as debt, that interest requires extraction, that asset bubbles are funded by credit, that their wages are structurally insufficient by design.
They paid the price for that ignorance in stress, in hardship, in lost opportunities, in lives shortened by deprivation-while others played a game with the system that enriched them far beyond anything they could ever need.
The system creates the struggle. Then it blames the struggling.
That is the betrayal.
6. The moral truth: legalised criminality
Calling this “legalised criminality” is not hyperbole. It is a description of the gap between legality and morality.
The system is legal because the law was written to protect it. The system is criminal in the human sense because it produces harm as a function of its design.
It has cost lives. It has denied peace of mind to millions. It has pushed people into debt, into hunger, into cold homes, into permanent anxiety, simply so that those playing a game with the system can make more and have more than they will ever need themselves.
Many of those who have picked up the intergenerational baton of financial control may not have been fully cognisant of the real‑world consequences of what they were doing. They may have believed the narratives of stability, responsibility, inevitability.
But ignorance is no excuse.
Power comes with responsibility. Paradigm blindness is no longer any kind of excuse when the consequences are fast becoming clear for all to see.
When belief sustains harm, and harm sustains wealth, legitimacy becomes a weapon.
People are suffering not because the system malfunctioned, but because it is functioning exactly as designed: to transfer wealth upward, to protect those who benefit, and to keep those who pay the price believing it is all somehow their fault.
7. The final question: can a system built on harm serve the public good?
The modern financial system is not a neutral tool. It is not a passive framework. It is not a natural evolution.
It is a mechanism-engineered, refined, and defended-that transfers wealth upward under the guise of legitimacy.
Its power comes from belief. Its consequences are real. Its impact is visible everywhere: in debt, in inequality, in collapsing services, in rising hardship, and in the ownership of the physical world.
People have been duped into thinking this is stability. But stability for the system has meant instability for everyone else.
So the question is no longer whether the system is moral.
The question is whether a system built on belief, extraction, and harm can ever truly serve the public good-and if not, what we are prepared to do once we finally see it for what it is.
A Reflection
It would have been very easy to write something that simply tears the economy apart, lists everything that is wrong, and leaves people with nothing but frustration – as too many still do. But that has never been my purpose. I am a solutions person. I believe in something better for everyone, and I have believed that for a long time.
I’ve been on the wrong end of the system myself, and my time as a councillor and local government officer brought me face to face with the cold, hard reality that the “legitimacy” of the system has carried enormous weight. It has taken many otherwise intelligent and caring people with it, convincing them that the harm it causes is somehow necessary, deserved, or is simply unavoidable.
I don’t agree.
The turbulence we are beginning to experience – and the uncertainty of what lies ahead – may offer humanity an opportunity for change of a kind it has never had before. That is why I have spent years developing structures and systems like the Basic Living Standard and the Local Economy and Governance System: practical foundations for a people‑first system rather than a money‑first one. These ideas are not abstract theories; they are workable designs for a fairer future.
I hope readers will take time to explore the work I have published, and I will always be happy to answer any questions I can. Understanding what has gone wrong is only the first step. What matters most is what we choose to build next.

